US auto-parts tariffs: why the factory’s exposure starts below the purchase order
The US tariff on specified automobile parts took effect on 3 May 2025, turning a policy announcement into an immediate supply-chain calculation. For manufacturers, the headline rate is only the beginning: product classification, origin eligibility, importer responsibility and the destination of the component can change the result.
As of May 7, 2025. The most useful response is a part-level assessment connected to production plans. A company-wide assumption that every imported component costs 25% more can be as misleading as assuming an established supplier route remains unaffected. Both shortcuts obscure which orders, customers and manufacturing decisions are actually exposed.
Start with the scope, not the supplier’s address
The March presidential proclamation introduced a 25% additional tariff on covered automobiles and specified automobile parts under Section 232. The automobile measure began on 3 April; implementation of the specified parts measure followed on 3 May. The covered products are defined through the tariff schedule and associated provisions, rather than through the everyday meaning of “automotive supplier”.
CBP’s updated guidance of 1 May identifies the relevant entry headings and distinguishes covered parts from articles that are not parts of passenger vehicles or light trucks. It also describes the treatment of qualifying USMCA parts, excluding knock-down kits and parts compilations from that exception. The relevant event is entry for consumption or withdrawal from warehouse for consumption, not simply the purchase-order date.
A purchasing database should therefore distinguish a supplier’s location from the facts used in customs treatment. An invoice from a North American distributor does not by itself establish that a component qualifies under USMCA. Conversely, a tariff heading shared with other industrial uses requires attention to the actual article and its use.
The April changes matter to the arithmetic
On 29 April, a further proclamation established an import adjustment offset linked to vehicles finally assembled in the United States. Eligible manufacturers may apply for an amount based on 3.75% of aggregate MSRP for the specified first period and 2.5% for the second. It is an offset against covered parts liability, with approvals, limits and designated importers, not a general reduction in every supplier’s invoice.
This distinction affects negotiations. A parts producer should not assume it can independently claim an automaker’s relief. A customer should not assume that an announced offset has already become available for a particular entry. The allocation and administration need to be confirmed through the relevant manufacturer and customs process.
A separate 29 April order addresses the stacking of specified tariff measures. Articles subject to the automobile measure are not also subject to the listed Canada, Mexico, steel and aluminium measures under the conditions set out in that order. Other applicable duties are not all erased. Adding every headline tariff together would therefore produce an unreliable landed-cost estimate.
An exposure register that operations can use
A useful register would connect each potentially affected part to its classification review, origin evidence, importer of record, entry timing and customer programme. It should also distinguish confirmed treatment from a question awaiting resolution. That separation prevents a planning assumption from quietly becoming an accounting fact.
The production link is essential. A low-value component used across many assemblies can deserve more attention than an expensive component used occasionally. The factory needs to know whether an unresolved customs issue affects a bottleneck part, a service requirement or an item with an already qualified alternative.
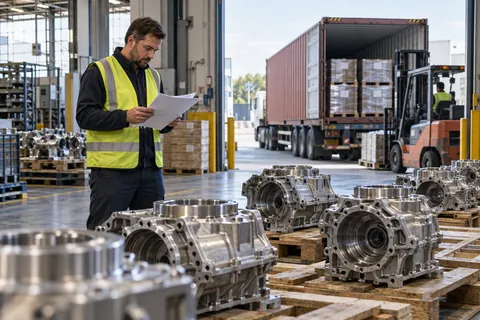
For illustration, imagine a manufacturer importing a cast housing and a sensor for the same vehicle assembly. Their commercial suppliers may sit in the same country while their tariff classifications and qualification records differ. Applying one supplier-level percentage to both would hide the very facts that determine treatment. The example is a planning scenario, not a customs classification of those products.
The register should have a named owner for each unresolved item. Finance can calculate the cash effect only after the relevant facts are established; engineering may hold the drawings needed to describe the article; procurement may hold origin documents. Passing the question repeatedly between departments adds delay without improving the evidence.
What research says about replacing an input
A February 2025 Federal Reserve research note examines how trade disruptions affect inflation. Its empirical work links measured trade costs to prices, while a separate multiregional model explores a US-China disruption scenario. The authors find a channel in which replacing intermediate inputs with imperfect substitutes reduces production efficiency and sustains cost pressure.
This is not a measurement of the May automobile-parts tariff. The model uses an illustrative shock and assumptions about substitution, and its inferred trade-cost measure has limitations. It nevertheless explains why a procurement saving cannot be assessed entirely at the border: changing an input can also change how efficiently the factory operates.
At plant level, the corresponding questions are concrete. Does the alternative fit the existing process? Does it require tooling changes, customer approval or a different inspection method? Can the supplier hold the required quality at the production rate? Those questions should be answered before a quoted tariff saving is treated as a realised manufacturing saving.
A sourcing proposal is stronger when it includes the cost and timing of qualification as well as the proposed purchase price. The research supports attention to this mechanism; it does not provide a universal percentage to add to every resourcing decision.
Compare complete scenarios
The factory can build a small set of scenarios around confirmed rules and explicit uncertainties. One might retain the existing supply route, another qualify an alternative, and a third adjust inventory while the commercial position is clarified. Each should use the same demand assumptions so that the comparison remains meaningful.
Costs to examine include the applicable duty, transport, inventory funding, tooling, validation, scrap during introduction and interruption risk. Some will be estimates rather than quotations. Showing those estimates separately helps the decision-maker see whether a sourcing recommendation depends on an optimistic launch assumption.
An illustrative alternative may have a lower landed purchase cost but require several months of engineering work. Another may cost more per piece yet be ready for an urgent production requirement. These are different decisions with different time horizons. A single blended annual number can conceal the short-term cash and capacity needed to reach the proposed steady state.
Scenario analysis should also test what happens if the policy changes. That does not mean predicting negotiations. It means identifying which commitments are reversible and which would leave the manufacturer with dedicated tooling or unusable inventory if the assumed advantage disappears.
Keep the customer discussion evidence-based
Commercial discussions become more productive when the supplier can distinguish a customs charge from freight, exchange-rate movement or an internal efficiency problem. Combining them in an unexplained surcharge makes it harder for a customer to verify the request or understand when it should change.
A practical discussion can identify the affected part numbers, the period covered and the assumptions used. Where offset eligibility is relevant, the parties can establish who will confirm it and how a later adjustment will be reconciled. The contract, rather than a generic industry headline, determines how the parties have allocated their commercial responsibilities.
The same discipline helps avoid overpromising. A supplier that has not yet confirmed the entry treatment should describe the uncertainty rather than guarantee an all-in price based on a favourable interpretation. A transparent provisional calculation gives both sides a basis for planning while the specific question is resolved.
Watch the entry and the production line together
As of early May, the immediate task is to connect customs implementation to the factory’s bill of materials and customer programmes. The updated CBP guidance, the April offset mechanism and the non-stacking order all matter to that work. None supports a blanket answer for every imported industrial component.
Manufacturers that keep a dated record of their assumptions will be better placed to revise decisions as guidance develops. The aim is to protect production continuity while understanding the true cost of each option. A tariff calculation becomes useful when it explains a real part, a real shipment and the manufacturing consequences of changing either.